Best RDSP Provider in Quebec: Our Top 10
Top 10 options for opening an RDSP in Quebec
Where to open an RDSP in Quebec? Desjardins, National Bank, TD, RBC, REEI.ca and more: support, fees and grants compared for 2026.

Short answer: for a family that wants help with both the Disability Tax Credit (DTC) and opening the RDSP, our first choice is REEI.ca. To manage a child’s investments yourself, look first at TD Direct Investing, since National Bank Direct Brokerage reserves its self-directed RDSP for adult beneficiaries. To stay with your current network, Desjardins and National Bank offer the RDSP with an advisor.
Key points
- Grants and bonds are set by the federal government: they are the same at every provider.
- According to Canada.ca, you do not need to already be a client of an institution to open an RDSP there.
- The beneficiary must be approved for the Disability Tax Credit (DTC) before the plan is opened.
- A beneficiary can only have one RDSP at a time. A direct transfer lets you change providers without losing your grants.
- What changes from one provider to another: the support you get, the investments offered and the fees.
Want support with the DTC and the RDSP?
Answer our online questionnaire, then a representative tells you the next steps. Getting started is free.
Check my eligibilityUpdated September 26, 2026.
Top 10 options for opening an RDSP in Quebec
This top 10 favours a guided path for Quebec families. It brings together banks, brokers and a firm that works through a partner issuer, so their roles are not identical. The features come from official pages consulted on September 26, 2026; links and detailed fees follow the table.
| Editorial rank | Option | Approach | Why consider it and what to check |
|---|---|---|---|
| 1 | REEI.ca | Remote DTC and RDSP support | A specialized firm that guides you, rather than an account you manage alone. Ask about investment fees and DTC service fees separately. |
| 2 | Desjardins | Desjardins Financial Centre advisor | To get support within the Desjardins network. Check the investments available and how grants are followed up. |
| 3 | National Bank | Advisor or direct brokerage | Two approaches. At NBDB, the self-directed RDSP is reserved for adult beneficiaries able to manage it. |
| 4 | TD Direct Investing | Self-directed online | To pick your own ETFs, stocks or other investments. You are responsible for monitoring the portfolio. |
| 5 | RBC Royal Bank | Branch advisor | GICs, mutual funds and other solutions. Get the transfer fee confirmed, since its pages contradict each other. |
| 6 | BMO | Support from a professional | GICs and investment funds. Ask for the total cost and the scope of RDSP follow-up. |
| 7 | CIBC | Opening by appointment | For an RDSP within the CIBC network. Ask which investments, which fees and who is responsible for your file. |
| 8 | Scotiabank | RDSP advisor | GICs, mutual funds and portfolios. Confirm how grant and bond applications are followed up. |
| 9 | IG Wealth Management | Advisor relationship | Worth considering if you already work with an IG advisor. Check their RDSP experience and the fees. |
| 10 | Empire Life | Segregated funds through an advisor | For a segregated fund offering. Compare the guarantees, their conditions and their costs. |
How we built this ranking
We looked at DTC and RDSP support, remote processes, access to an advisor, investments and published fees. REEI.ca comes first for families who want to delegate the paperwork: it is our specialty, and the families we support give us a 5.0 rating across more than 1,500 Google reviews. The following ranks present other options by service model; they do not prove that one institution is better than another.
We do not give scores out of 100: without a comparable test of service, timelines and real costs, they would create false precision. Mackenzie, a partner listed by REEI.ca, is described further down as an issuer reached through an advisor, rather than being counted a second time in the top 10.
Which institutions offer the RDSP in Quebec?
The federal list includes 17 organizations that agreed to appear on it. It covers banks, fund companies, an insurer and brokers. Some firms open RDSPs through these issuers without appearing on the list themselves.
The table reproduces the federal list of organizations that offer the RDSP. According to Canada.ca, you do not need to already have an account there. The list does not guarantee that every organization serves all clients in Quebec.
| Organization | Type | What to know in Quebec |
|---|---|---|
| Desjardins | Financial cooperative | Opened by a Desjardins Financial Centre advisor |
| Natcan Trust Company | National Bank Group | National Bank’s RDSP; self-directed accounts go through National Bank Direct Brokerage |
| RBC | Bank | In branch or by phone |
| TD Waterhouse Canada | Brokerage (TD) | Self-directed RDSP online at TD Direct Investing |
| BMO Bank of Montreal | Bank | With a BMO professional |
| CIBC | Bank | By appointment or by phone |
| Scotiabank | Bank | RDSP advisor |
| Mackenzie Financial Corporation | Fund company | Through an advisor only |
| IG Wealth Management | Wealth management | Separate phone line for Quebec |
| The Empire Life Insurance Company | Insurer | Through an advisor, in segregated funds |
| Fonds FMOQ | Fund company | Appointment with a Fonds advisor |
| Aviso Financial | Financial services | Contact them directly for terms |
| CI Investment Services | Investment firm | Contact them directly for terms |
| Leede Jones Gable | Broker | Contact them directly for terms |
| ATB Securities | Broker | Service in English only |
| Concentra Bank | Bank | Service in English only |
| Central 1 | Credit unions | Ontario and British Columbia only |
Canada.ca specifies that this list is not a promotion. It compares neither fees nor service.
Desjardins, National Bank, TD, RBC: what does each institution offer?
Advisor or self-directed, the services differ. Here are the investments and fees shown on the official pages. Confirm the conditions that apply to your RDSP before signing.
| Institution | How to open | Investments mentioned on the official page | Published fees |
|---|---|---|---|
| Desjardins | Financial Centre advisor | Term savings, market-linked guaranteed investments, stable savings account | Not specified on the RDSP page |
| RBC Royal Bank | In branch or by phone | GICs, mutual funds, portfolio solutions, savings deposits | No annual administration or withdrawal fees, according to RBC; fee to transfer out of RBC, amount to confirm |
| TD Direct Investing | Online, self-directed | Stocks, ETFs, mutual funds, fixed income, GICs, options | $0 on select ETFs; $9.99 per trade on stocks |
| National Bank Direct Brokerage | Self-directed, by contacting NBDB | Stocks, ETFs, investment funds, GICs (NBDB general pricing) | $0 commission on online stocks and ETFs; $100 per year unless exempt |
| BMO | With a BMO professional | GICs, investment funds | Not specified on the RDSP page |
| CIBC | By appointment or by phone | Investment accounts at CIBC Investments or CIBC Investor Services | Not specified on the RDSP page |
| Scotiabank | RDSP advisor | GICs, mutual funds, Scotia Essentials Portfolios | Not specified on the RDSP page |
Fees observed on the official pages on September 26, 2026. They can change: confirm the schedule that applies to your RDSP before signing.
Desjardins RDSP: how to open one
At Desjardins, the plan is opened through a Desjardins Financial Centre advisor. Desjardins’ RDSP page describes three steps: discuss your needs, choose the investments, then contribute, as one-time or automatic deposits. It highlights guaranteed products. If you are aiming for growth over 20 or 30 years, ask for the full list of eligible investments. We did not find an RDSP among the accounts offered by Desjardins Online Brokerage.
National Bank RDSP: advisor or direct brokerage
With an advisor, National Bank appears on the federal list through its Natcan Trust Company. For self-directed investing, National Bank Direct Brokerage (NBDB) states on its forms page that its self-directed disability savings plan is “available only to beneficiaries of legal age who are able to manage the account themselves.” A parent opening a plan for a minor child must therefore look elsewhere to manage the investments personally.
NBDB’s pricing advertises $0 commission on online stocks and ETFs. An administration fee of $100 per year applies, however, unless you meet an exemption criterion, such as holding $20,000 in eligible assets on May 31.
TD RDSP: self-directed online with TD Direct Investing
TD Direct Investing’s RDSP page lets you open a self-directed RDSP online and hold stocks, ETFs, mutual funds, fixed income or GICs in it. Its pricing shows $0 commission on a selection of ETFs, not all of them, and $9.99 per stock trade for a standard investor.
A maintenance fee of $25 per quarter applies when the balance is under $15,000. TD waives it through its household account program, and holding an RDSP is one of the qualifying criteria. Our view: it is an accessible self-directed option for a parent comfortable with ETFs, provided someone reviews the portfolio every year. Still compare the processes and real fees before choosing.
RBC, BMO, CIBC and Scotiabank RDSPs: the advisor approach
RBC’s RDSP page offers pre-authorized contributions starting at $25 per week and says no annual administration or withdrawal fees apply. For a transfer to another institution, that page shows a $150 fee, while RBC’s investment FAQ mentions a $50 fee. Ask for the applicable amount in writing.
BMO offers GICs and investment funds with one of its professionals. CIBC holds its RDSPs in investment accounts at CIBC Investments or CIBC Investor Services. Scotiabank offers GICs, mutual funds and portfolios that combine ETFs and funds.
Mackenzie, IG and Empire Life RDSPs: through an advisor
Mackenzie and Empire Life work through advisors. Mackenzie’s RDSP FAQ indicates that clients must go through their advisor to set up a plan. Empire Life offers an RDSP in segregated funds, opened online by the advisor. This route suits you if you already have a trusted advisor who knows the RDSP rules well.
Why the first contact at an institution can be difficult
Your bank may offer the RDSP, but the first person you reach is not necessarily a specialist in the plan. The federal evaluation of the Canada Disability Savings Program published in 2025 reports difficulty finding sufficiently knowledgeable staff, which delayed some openings.
The report qualifies this finding: several informants did not distinguish front-line staff from centralized RDSP teams, and recent experiences reported fewer obstacles. So it is not proof that bank advisors know the plan poorly.
- Find the right contact. Some participants had to reach a specialist in another city or province, with scheduling or communication difficulties. Ask who will actually handle your file.
- Name the right plan. Say “Registered Disability Savings Plan”, not just an acronym. The RESP is for education. So do not rely on a comparison of RESP providers to choose your RDSP.
- Define the follow-up. Ask who checks carry-forward entitlements, forms and deadlines. Opening an account does not by itself show that all this support is included.
A specialized firm can simplify this path by bringing DTC and RDSP support together. This guarantees neither DTC approval nor a specific timeline; the benefit is knowing who to ask and who helps you move forward.
Self-directed RDSP or with an advisor: which to choose?
Self-directed investing works if someone can choose and monitor the investments over the long term. Otherwise, consider an advisor. Neither route is safer in itself: the beneficiary’s time horizon and the annual follow-up are what matter.
The trap of self-directed investing, in our view, is not the stock market, it is forgetting. A contribution missed before year-end, a portfolio never reviewed, or a step missed at adulthood. Canada.ca specifies that, to keep receiving the right amounts from age 19, the beneficiary must file tax returns, starting in the year they turn 17, and personally sign the grant and bond application with their institution.
| Criterion | Self-directed RDSP | RDSP with an advisor |
|---|---|---|
| Who chooses the investments | The holder, online | The holder, on an advisor’s recommendation |
| Costs to check | Commissions, account fees, ETF management fees | Fund management fees, advisor compensation |
| Follow-up of grants and deadlines | Up to you | Scope of follow-up to confirm in writing |
| Change of holder (age of majority, guardianship) | Check with the broker | The advisor guides you |
| Suits you if | Someone enjoys managing investments and will do it for a long time | You want to delegate or be reassured at each step |
Does the choice of institution change the grant amount?
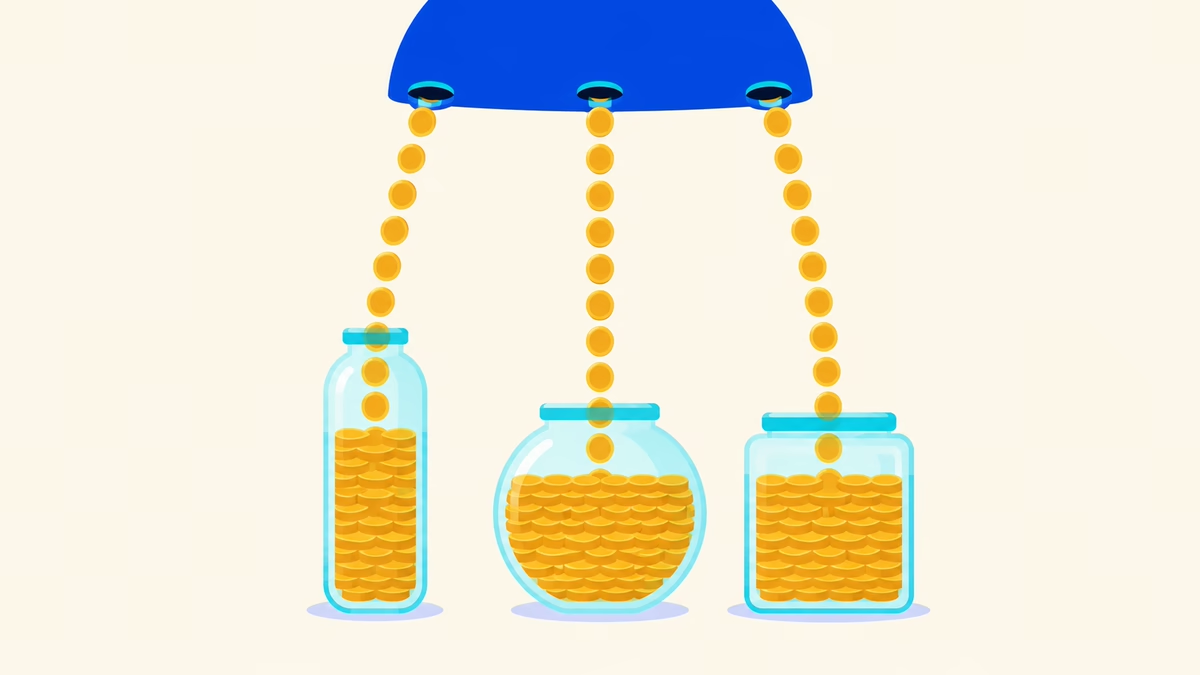
No. The federal government sets the grant according to family income and your contributions, and the bond according to family income only, with no contribution needed. The institution changes nothing. No bank or firm can get you more than your entitlement. A good provider does, however, help you forget nothing: the initial application, carry-forward entitlements and the steps at age 19.
Here are the 2026 rules published by Canada.ca on grants and bonds. The family income used is the one from the 2024 tax return.
| Family income | Annual grant | Contribution to get the maximum | Annual bond |
|---|---|---|---|
| $38,237 or less | $3 per $1 on the first $500, then $2 per $1 on the next $1,000, up to $3,500 | $1,500 | $1,000, no contribution needed |
| Over $38,237 and under $58,523 | Same calculation, up to $3,500 | $1,500 | Partial bond, decreasing as income rises |
| $58,523 to $117,045 | Same calculation, up to $3,500 | $1,500 | No bond |
| Over $117,045 | $1 per $1, up to $1,000 | $1,000 | No bond |
The grant is capped at $70,000 for life and the bond at $20,000. Entitlements from the last 10 years can be carried forward, but the government pays no more than $10,500 in grants in a single year, carry-forward included. Our RDSP calculator helps you estimate these amounts.
For past years, also see our guide on the retroactive Disability Tax Credit.
Grants are the same everywhere. Support is not.
We help you meet the conditions for opening, apply for the grant and bond, and remember eligible carry-forward entitlements.
Start my file onlineWhich fees should you compare before opening an RDSP?
Compare the total cost, not just the opening: account fees, commissions, fund management fees, advisor compensation and transfer fees. On an RDSP that stays invested for 20 or 30 years, a gap in annual fees weighs heavily, because it repeats every year. Always ask for a written breakdown, based on your actual investments.
| Fee | Example observed on September 26, 2026 | Question to ask |
|---|---|---|
| Account or administration fees | NBDB: $100 per year unless exempt. TD: $25 per quarter under $15,000, can be waived | Do these fees apply to my RDSP, and how can I avoid them? |
| Buy and sell commissions | TD: $0 on select ETFs, $9.99 on stocks. NBDB: $0 on online stocks and ETFs | How much will my actual activity cost each year? |
| Fund management fees | Built into the returns of mutual funds and ETFs | What is the management expense ratio of each fund proposed? |
| Advisor compensation | Varies by institution | How is the advisor paid, and what follow-up is included? |
| Transfer to another institution | RBC: $150 on its RDSP page, $50 in its FAQ | What is the exact amount, and can my investments be transferred without selling? |
An example shows why. Suppose a $1,500 contribution and a $3,500 grant per year, or $5,000 per year for 20 years. With a hypothetical gross return of 6% per year, total fees of 0.5% leave about $174,300. Fees of 2% leave about $148,900. The gap, about $25,400, represents almost 17 years of the family’s contributions.
Illustrative example: year-end deposits, constant return, no withdrawals. This is neither a forecast nor a promise of returns.
The cheapest option does not always win. An advisor can be worth their fees if they help you avoid a costly mistake. Just know what you are paying and what follow-up is included.
Wealthsimple, Questrade, RESP: which mistakes to avoid?
Check the actual offering and the name of the plan. The following mistakes can steer you to the wrong product or the wrong provider.
- Wealthsimple: its Choose an account to open page, updated September 24, 2026, does not include an RDSP.
- Questrade: the RDSP does not appear on its account types page, consulted on September 26, 2026.
- RESP and RDSP: the first is for education, the second for the financial security of a person eligible for the Disability Tax Credit. A comparison of RESP providers tells you nothing about the RDSP.
- NBDB for a child: self-directed investing at NBDB is reserved for adult beneficiaries able to manage the plan.
- “More grants elsewhere”: false, the amounts are set by the federal government.
Can you change RDSP providers without losing your grants?
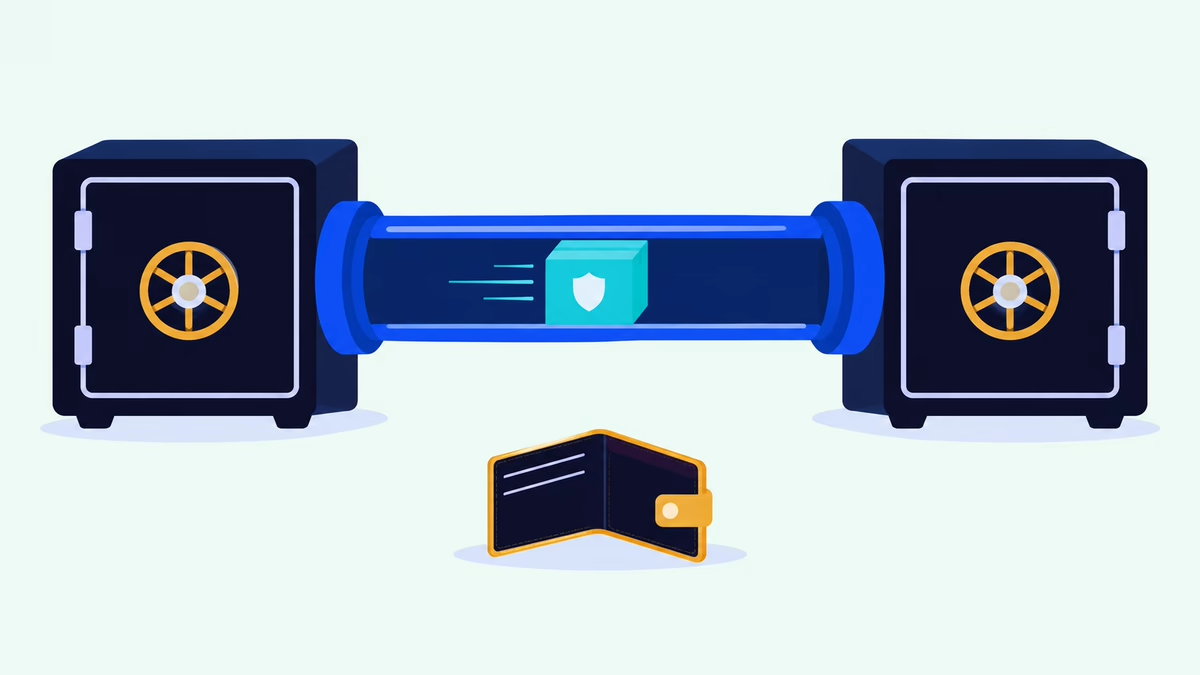
Yes, through a direct transfer from one RDSP to another for the same beneficiary. The transfer must cover the entire plan, and the holder requests it, using the forms of both institutions. Never withdraw the money yourself to deposit it elsewhere: a withdrawal can trigger the repayment of grants and bonds.
According to Canada.ca’s page on transferring a plan, you cannot transfer only part of an RDSP, and institutions may impose conditions and fees. A beneficiary can hold only one RDSP at a time, except during a transfer. Closing an RDSP for any reason other than a transfer requires you to repay the grants and bonds paid in the previous 10 years.
- Confirm that the new provider accepts the transfer and your current investments.
- Fill out the forms required by both institutions.
- Ask in writing about fees, timelines and how investments that cannot be transferred will be handled.
- Ask whether new grant and bond forms must be completed.
- Keep your statements and follow up until the transfer is confirmed.
Our view: if a young beneficiary’s RDSP has been sitting for years in a savings account or a short-term GIC, a review is in order. A transfer is not always the answer, but the question is worth asking.
Why open your RDSP with REEI.ca?
For a simple, remote path, with a team that knows the RDSP. You start with our online eligibility questionnaire, from home, then talk with a representative. Our goal is to spare you scattered steps and branch visits. Timelines also depend on documents and government decisions.
The DTC and the RDSP are part of the same path, but they are not the same benefit. We support you with your Disability Tax Credit application. Depending on the approved years and your tax situation, retroactive adjustments may be possible for up to 10 years. A tax refund is not an RDSP grant, and no amount is guaranteed.
Once the conditions for opening are met, we support you with the plan and the grant and bond applications, including eligible carry-forward entitlements. The federal rules remain the same for everyone.
People who also understand disability from the inside. The public profile of Ludovic, an RDSP advisor, notably describes his physical limitations. Our representatives are certified with the Autorité des marchés financiers, Quebec’s financial regulator.
REEI.ca lists Mica and Mackenzie Investments among its partners. Ask in writing for the issuer of your RDSP, the investments proposed, their management fees and the compensation tied to the advice. For the DTC, getting started is free: according to our DTC page (in French), if we do not help you obtain a refund or additional benefit, our services cost you nothing. Ask for the fees that would otherwise apply in writing.
We are not a self-directed broker. If your priority is buying your own ETFs, TD Direct Investing or NBDB may better meet that need. Also see our step-by-step guide to opening an RDSP before choosing.
Frequently asked questions
Which banks offer the RDSP in Quebec?
Desjardins, National Bank, RBC, TD, BMO, CIBC and Scotiabank all offer the RDSP in Quebec. The federal list also includes fund companies, an insurer and brokers, such as Mackenzie, IG and Empire Life. According to Canada.ca, you do not need to already have an account there to open a plan.
What is the best RDSP provider in Quebec?
For a family that wants support with both the DTC and the RDSP, our choice is REEI.ca: a specialized team, remote processes and a 5.0 rating across more than 1,500 Google reviews. To manage your investments yourself, compare self-directed brokers instead. Federal grants follow the same rules everywhere.
Can you have more than one RDSP?
No. A beneficiary can hold only one RDSP at a time, except during a transfer from one plan to another. If you change providers, the entire plan must be transferred directly, then the old RDSP is closed. You cannot split an RDSP between two institutions.
Does Wealthsimple offer the RDSP?
Not according to its official list of accounts, updated September 24, 2026, which does not include an RDSP. For a self-directed RDSP online, look instead at TD Direct Investing, or National Bank Direct Brokerage if the beneficiary is an adult able to manage the plan personally.
Can you open an RDSP at Desjardins?
Yes. Desjardins opens the RDSP through a Desjardins Financial Centre advisor, reachable at 1-877-286-3420. Its RDSP page highlights guaranteed products. We did not find an RDSP among the accounts offered by Desjardins Online Brokerage. To manage investments yourself, compare a self-directed broker instead.
How much does it cost to open an RDSP?
The official pages we consulted show no opening fee, but other costs can apply: account fees, commissions, fund management fees and transfer fees. For example, NBDB charges $100 per year unless exempt. Ask for a written breakdown of the total cost before signing.
Can you open an RDSP online?
Yes, in two ways. TD Direct Investing lets you open a self-directed RDSP online if you choose the investments yourself. With REEI.ca, you start with an online questionnaire, then a representative supports you remotely with the DTC and opening the plan. The beneficiary must first be approved for the DTC.
Start your RDSP with REEI.ca
Want support without multiplying the steps? Fill out our online eligibility questionnaire. We will help you clarify the next steps: DTC, opening the RDSP and applying for government support. Before committing, get the included services and all applicable fees confirmed. The right path is the one you understand and can follow.