How to Apply for the Canada Disability Savings Bond: A Step-by-Step Guide
What is the correct order for applying for the Canada Disability Savings Bond?
Learn how to apply for the Canada Disability Savings Bond: get DTC approval, open an RDSP, and request the bond through your financial institution.


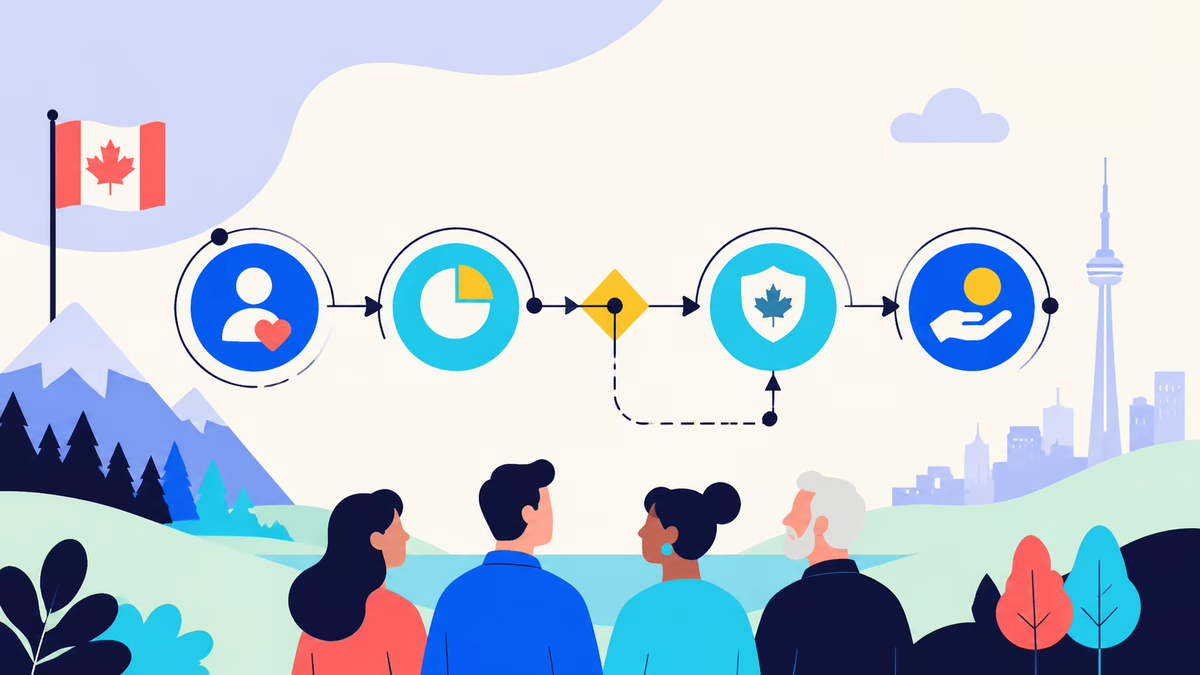
The correct order is simple: first obtain approval for the Disability Tax Credit, then open a Registered Disability Savings Plan with a participating financial institution, and finally request the Canada Disability Savings Bond through that RDSP. You do not apply for the bond as a separate standalone benefit or ask CRA to deposit it directly.
What is the correct order for applying for the Canada Disability Savings Bond?
Start with the Disability Tax Credit, move to an RDSP, and ask the financial institution to submit the bond request through that plan. This sequence matters because the bond is an RDSP payment. The institution needs an eligible beneficiary and a registered plan before it can send the request into the federal process.
People often search for a bond form first, but that reverses the process. The bond is connected to the beneficiary’s RDSP, not to a separate account. Use the checklist below as a simple gate-by-gate route.
| Order | What must happen | Who starts it | What it unlocks |
|---|---|---|---|
| First | Apply for and receive DTC approval | Beneficiary or representative, with medical practitioner | Eligibility to open and maintain an RDSP |
| Second | Choose a participating financial institution and open an RDSP | Plan holder and institution | A registered plan linked to the beneficiary |
| Third | Request the bond through the RDSP | Plan holder and institution | Review by the federal program for payment into the plan |
| Ongoing | Keep tax, identity, and plan information current | Holder, beneficiary, institution, and government partners | Continued assessment of eligibility and available entitlements |
For a plain-language explanation of how the bond differs from the Canada Disability Savings Grant, read Reei.ca’s grant and bond overview. This procedure page stays focused on the bond request itself.
Why must the Disability Tax Credit come first?
DTC approval is the prerequisite for an RDSP. The Disability Tax Credit is a federal tax measure based on the effects of a severe and prolonged impairment, as certified through the CRA process. Without DTC approval, the financial institution cannot establish the RDSP pathway needed for a bond request.
The first practical task is therefore the DTC application. A medical practitioner completes the relevant section describing the impairment’s effects, while the applicant or representative completes the personal and consent information. CRA reviews the application and communicates its decision. Approval is not automatic, and it is not the same as approval for another disability program.
Use the current Form T2201 page on Canada.ca for the official form and instructions. Since July 14, 2026, CRA’s Submit documents function cannot be used to send a DTC application unless CRA specifically requested more information. If you apply on paper, use the latest version accepted by CRA. Older pre-2023 versions are no longer accepted as of September 8, 2026.
Keep the CRA decision and the approved period with your records. The institution may need the DTC status or related identifiers when preparing the RDSP. If you need help organizing the DTC stage, Reei.ca offers DTC application support before you move to the plan-opening stage.
How do you open the RDSP that carries the bond request?
After DTC approval, contact a financial institution that offers RDSPs and ask to open a plan for the approved beneficiary. The institution becomes the issuer or works with an issuer, sets up the account, confirms the holder, and connects the beneficiary’s information to the plan. This is where the bond request can be made.
Compare participating institutions by asking about investment choices, account administration, fees, accessibility, and the support available for grant and bond applications. Reei.ca’s RDSP opening service can help families prepare for this conversation, but the financial institution remains responsible for establishing the account and submitting the official request.
The holder is the person or organization authorized to manage the RDSP. The beneficiary is the person whose DTC approval supports the plan. A parent, legal representative, or public institution may have a role in some situations. Do not guess who can sign. Tell the institution about the beneficiary’s age, capacity, and representation status so it can identify the correct holder process.
The institution will collect information about the beneficiary, holder, and any applicable primary caregiver or representative. It will also explain its consent process, investment setup, and documents. Read the plan agreement carefully. Opening the plan and requesting the bond are related steps, but they are not the same record or decision.
| Stage | Beneficiary or family | Financial institution | Government partner |
|---|---|---|---|
| Prepare | Confirm DTC approval, identity, tax details, and authority to act | Explain available RDSP setup and document requirements | CRA maintains DTC and tax information |
| Open | Choose the holder and provide consent or representation documents | Registers the RDSP and records the beneficiary and holder | CRA recognizes the registered plan under the federal rules |
| Request | Review and authorize the bond application | Completes and submits the bond request through the plan | ESDC administers the federal grant and bond system |
| Maintain | Report changes and keep tax filings current | Tracks plan activity and communicates account information | Government partners reassess available entitlements using current information |
How is the bond requested through the RDSP?
The holder asks the financial institution to apply for the bond as part of the RDSP setup or through the institution’s follow-up process. The institution sends the required plan and beneficiary information to the federal program. If the request is accepted, the bond is paid into the RDSP, where it remains subject to plan rules.
There is no separate cheque or personal-bank-account application for the bond. The financial institution is the operational bridge between the holder and the federal program. Give complete, consistent information and review every form before signing or providing consent. Ask for a copy of the submitted request and keep the institution’s confirmation with the DTC decision.
Eligibility and available entitlements can depend on family income information from relevant tax years, DTC status, residency, the beneficiary’s Social Insurance Number, and the plan’s registration. The institution may need to resolve an information mismatch before it can submit or before a payment can be made. That is why accurate records matter more than finding a standalone bond form.
If you are opening an RDSP from Quebec, the federal sequence is the same: DTC approval, RDSP opening, then a request through the participating institution. The institution can explain its products and administration in Quebec. For a second opinion on the setup, use Reei.ca’s English application support rather than starting a second government application.
What should you prepare before meeting the financial institution?
Prepare the records that establish who the beneficiary is, who can act for them, and whether the DTC prerequisite is in place. Bring the CRA decision, identification, Social Insurance Number, tax information, and representation documents where relevant. Also prepare questions about fees, investments, statements, and how the institution submits the request.
| Bring or confirm | Why it matters | Who may provide it |
|---|---|---|
| DTC approval information | Shows the federal prerequisite for the RDSP route | Beneficiary or representative |
| Social Insurance Number and identification | Lets the institution match the people and plan records | Beneficiary, holder, and representative as applicable |
| Tax and family-income information | Supports the federal assessment of bond eligibility and entitlements | Beneficiary, holder, or tax records |
| Authority or representation documents | Shows who can open and manage the plan | Parent, guardian, legal representative, or public institution where applicable |
| Institution questions | Helps compare fees, investments, access, statements, and support | Beneficiary, family, or adviser |
Do not send personal documents to an unofficial address. Confirm the institution’s secure submission method and ask whether originals, copies, or electronic records are required. Reconcile names and identification details across the DTC decision, tax records, and plan application before submission.
How can you verify the current bond rules without relying on an old article?
Use Reei.ca for the sequence and Canada.ca for current program figures and eligibility rules. Bond amounts, income thresholds, annual limits, lifetime limits, and carry-forward details are indexed and may change. This article intentionally states zero bond dollar figures and thresholds. Confirm the current values on the official RDSP pages before deciding.
Start with the Government of Canada’s RDSP program page, which explains how to open a plan and how grants and bonds fit into it. Then check the official grants and bonds amount page for the figures and income rules that apply when you read it.
The CRA’s RDSP overview is useful for plan rules, payments, tax treatment, and situations that can affect an RDSP. Bookmark the pages rather than copying figures into a personal checklist. A value that was correct for one tax year may be outdated later.
| Question to verify | Official place to check | Why the check matters |
|---|---|---|
| What bond amount and income rule apply now? | Canada.ca grants and bonds amount page | Figures and thresholds are indexed and can change |
| Can the beneficiary open an RDSP? | Canada.ca RDSP program and CRA RDSP pages | DTC, residency, identity, and plan conditions must align |
| What documents or consent does the plan require? | Chosen financial institution | Institutions use their own secure application and verification process |
| What happens if plan circumstances change? | CRA RDSP overview and plan issuer | Withdrawals, DTC changes, transfers, and closures can affect plan rules |
What should you do after the bond request is submitted?
Keep the submitted application, confirmation, and plan documents together, then review the RDSP statement when the institution records the result. If something is missing or inconsistent, contact the institution first because it submitted the request. For federal rule questions, compare the response with the current Canada.ca RDSP pages rather than an old forum or calculator.
Check that the beneficiary’s name, Social Insurance Number, holder details, DTC status, and tax information are consistent. Tell the institution about changes that may affect the plan. Do not make a withdrawal or close the RDSP based on a generic online answer. Ask how the proposed action could affect grants, bonds, repayments, or future eligibility.
For planning, Reei.ca’s RDSP calculator can help frame questions, but it is not a substitute for the current figures on Canada.ca or the institution’s calculation. Use it as a conversation aid, especially when family income or past DTC eligibility has changed.
What are the most common questions about applying for the Canada Disability Savings Bond?
Can I apply for the Canada Disability Savings Bond directly?
No. The bond is not a standalone application. First, the beneficiary must be approved for the Disability Tax Credit. Next, a participating financial institution opens an RDSP. The holder then requests the bond through that plan, usually with the institution’s application and supporting information.
Do I have to contribute money to receive the bond?
The bond is designed for eligible low-income and modest-income beneficiaries and does not require an RDSP contribution. A contribution may matter for the separate Canada Disability Savings Grant, which follows different rules. Review both programs separately on Canada.ca before making a savings decision.
What information should I bring to the financial institution?
Bring the beneficiary’s DTC approval information, Social Insurance Number, identification, tax and family-income details, and the information needed for the plan holder. If a parent, guardian, or legal representative is involved, bring documents proving that authority. The institution will confirm its exact checklist.
Does the CRA pay the bond into my bank account?
No. The bond is deposited into the beneficiary’s Registered Disability Savings Plan, not paid as a standalone deposit to a personal bank account. The financial institution administers the plan and submits the request through the federal program. Account statements should show plan activity after processing.
Where can I check current bond amounts and income rules?
Use the Government of Canada’s current RDSP pages for bond amounts, income rules, annual limits, lifetime limits, and carry-forward details. These figures are indexed and can change. Reei.ca explains the process, but Canada.ca is the source to confirm the figures that apply today.
What if I have not filed my tax returns recently?
Ask the financial institution or a qualified adviser how missing tax information affects the request. The program uses government records to assess eligibility and entitlements. Do not assume an old income figure still applies. Confirm what must be filed or updated before asking the institution to submit.