Understanding the Disability Tax Credit in Canada
What is the Disability Tax Credit in Canada?
The Disability Tax Credit explained plainly: why non-refundable matters, the 2025 amounts, the two-step process, and what approval unlocks for an RDSP.

The Disability Tax Credit is a federal non-refundable tax credit for people living with a severe and prolonged impairment. Approval does not send you a monthly payment. It lowers the income tax you owe, opens the door to an RDSP, and can be claimed retroactively for up to 10 years.
What is the Disability Tax Credit in Canada?
The Disability Tax Credit, or DTC, is a federal credit that reduces income tax for people whose impairment markedly restricts daily living. A medical practitioner certifies the effects on Form T2201, the Canada Revenue Agency decides eligibility, and the approved person or a supporting family member claims the amount each year.
Two ideas get mixed up constantly. Eligibility is a decision the CRA makes once, after reviewing a certification. The claim is something that happens every year afterward, on the tax return. You can be approved and still see nothing change until the return is filed and the amount is entered on the right line.
The credit is built around the effects of an impairment, not around a diagnosis. Two people with the same condition can get different answers, because the question is how the impairment restricts daily living, how long it has lasted, and whether it is expected to continue. That is also why a strong certification matters more than a long medical history.
Severe and prolonged are the two words that carry the decision. Severe points to a marked restriction in a basic activity of daily living, or to the cumulative effect of several significant restrictions taken together. Prolonged points to duration, meaning the impairment has lasted or is expected to last over a long period rather than passing. The basic activities the CRA looks at include walking, dressing, feeding, elimination, hearing, speaking, vision and mental functions necessary for everyday life, plus a separate route for people who need life-sustaining therapy.
This article covers the federal credit. Provincial and territorial disability amounts exist as well, they vary by province, and Quebec administers its own provincial credit through its own return.
How does the two-step apply-then-claim process work?
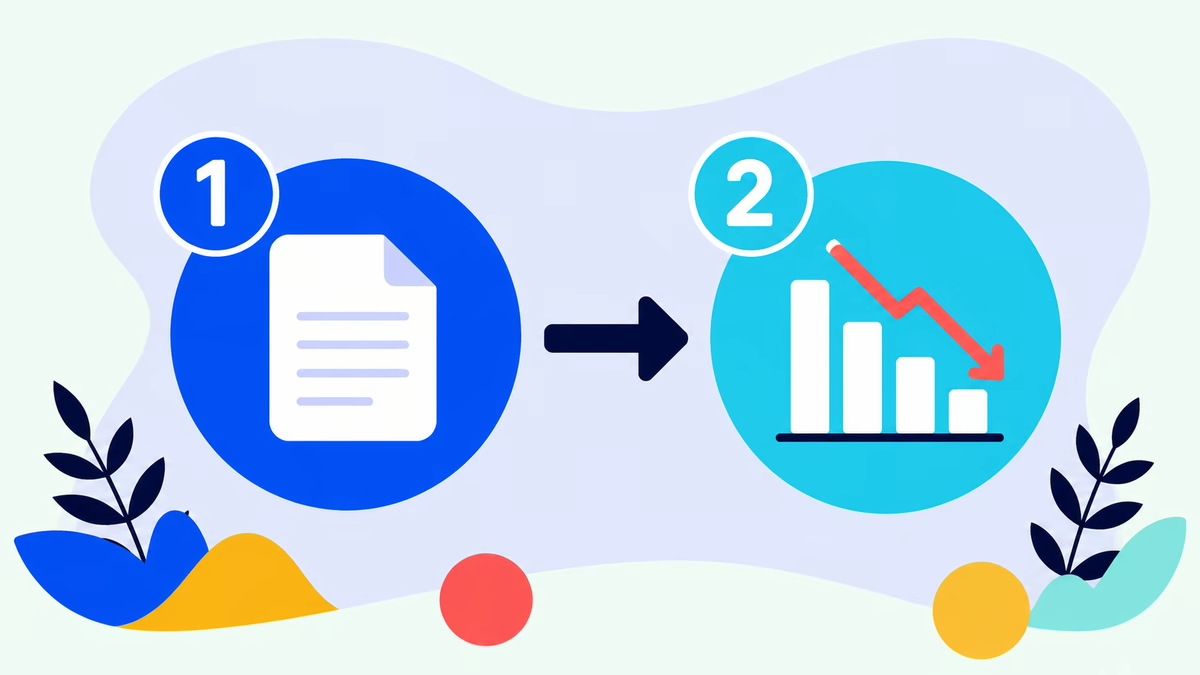
Getting the credit takes two separate steps. First you apply, which means a medical practitioner certifies how the impairment affects you on Form T2201 and the CRA reviews that certification. Second, once you are approved, you claim the disability amount on your tax return for every year you qualify.
| Stage | Who does the work | What it produces |
|---|---|---|
| Step 1, apply | You or your representative complete Part A, a medical practitioner completes Part B of Form T2201 | A certified application the CRA can assess |
| Review | The Canada Revenue Agency | A decision letter stating whether you are eligible and which years are covered |
| Step 2, claim | You, or a spouse, common-law partner or supporting family member | The disability amount entered on the return, reducing federal tax payable |
| Past years | You, by asking the CRA to adjust earlier returns | Reassessments and refunds for approved years, up to 10 years back |
Missing the second step is the most common way people leave money behind. A decision letter arrives, it gets filed away, and the return is prepared without the amount. Nothing in the system claims it for you. If the approval covers earlier years, those returns have to be adjusted one by one.
You can start the application through the DTC application service if you want the paperwork handled with you rather than alone at a kitchen table.
What does non-refundable mean for the Disability Tax Credit?
Non-refundable means the credit can lower your tax bill to zero, but it never turns into a cheque on its own. The disability amount reduces federal tax by roughly $1,500 at the 15 percent rate. If you owe less tax than that, the unused part is simply not paid out.
| Federal tax owing before the credit | What the credit does | What you end up with |
|---|---|---|
| More than $1,500 | Applies in full | Federal tax drops by roughly $1,500 |
| Less than $1,500 | Applies only up to the tax actually owed | Tax falls to zero, the remainder is not refunded to you |
| Nothing owing | There is no tax to reduce | No federal reduction that year, though the amount may be transferable |
That last row is where the confusion starts. Someone with little or no taxable income hears the words tax credit and expects a deposit. It does not work that way. What rescues the situation is the transfer rule, which lets a spouse, common-law partner or supporting family member use the unused amount against their own tax.
Retroactive approvals are the exception that feels like a refund, and they genuinely are one. If you already paid tax in earlier years and the CRA approves you for those years, adjusting those returns lowers tax that was assessed and paid, so money comes back. The credit did not become refundable, you simply overpaid at the time.
One more correction is worth making here, because it changes the arithmetic people do in their heads. The DTC is a credit, not a deduction. A deduction lowers the income that gets taxed. A credit is applied against the tax itself, at a fixed rate, after the tax has been calculated. That is why the value of the disability amount does not climb with a higher income the way a deduction would, and why the same amount is worth the same federal reduction to a nurse and to a lawyer.
How much is the disability amount worth each year?
For the 2025 tax year the disability amount is $10,138 for an adult. A child under 18 can also claim a supplement of $5,914, for a combined $16,052. Amounts are indexed each year, so a retroactive approval uses the figure that applied to each past year you claim.
| Tax year | Disability amount | Supplement, child under 18 |
|---|---|---|
| 2025 | $10,138 | $5,914 |
| 2024 | $9,872 | $5,758 |
| 2023 | $9,428 | $5,500 |
| 2022 | $8,870 | $5,174 |
| 2021 | $8,662 | $5,053 |
| 2020 | $8,576 | $5,003 |
| 2019 | $8,416 | $4,909 |
| 2018 | $8,235 | $4,804 |
| 2017 | $8,113 | $4,733 |
| 2016 | $8,001 | $4,667 |
Read those as amounts, not as money in hand. The federal non-refundable rate is about 15 percent, so the adult amount translates into roughly $1,500 of federal tax reduced in a year where enough tax is owed. Provincial and territorial credits sit on top of that and vary, which is why two households with identical federal numbers can still land in different places.
The supplement for a child under 18 has a catch worth knowing before you plan around it. It is reduced when someone claimed child care expenses on line 21400 or attendant care expenses on line 33099 or 33199 for that child during the year, or when the child claimed attendant care expenses on line 21500 or 33099. Families using paid care often see a smaller supplement than the headline figure.
The CRA page for line 31600 sets out the current amount, and the claiming the DTC page lists the earlier years. If you want a rough figure for your own situation before filing, the DTC calculator is a faster starting point than a spreadsheet.
One practical note on the years. The decision letter states which years the approval covers, and eligibility is not always granted permanently. When a period ends, a fresh certification is needed to keep claiming. Read that letter carefully instead of filing it, because the years it lists are exactly the years you can claim.
Who certifies the impairment, and what is changing with Form T2201?
A medical practitioner certifies the effects of the impairment in Part B of Form T2201. Only the CRA decides eligibility. Since July 14, 2026 the submit documents tool cannot be used for DTC applications unless the CRA asked for more information, and older T2201 versions are refused after September 8, 2026.
Those two changes matter right now. If you are working from a printed form that has been sitting in a folder, check the version before mailing it. Anything published before 2023 stops being accepted on September 8, 2026, and a refused form means starting over rather than being corrected. The current version is on the CRA Form T2201 page.
The CRA states that the online application in a CRA account is processed faster than paper. Paper applicants download the latest form and mail it to their tax centre. The CRA tax tip on speeding up a DTC application covers both routes.
Practitioners can charge for completing the form. That fee is a medical expense, claimable on line 33099 or 33199 like other eligible expenses, so keep the receipt with the rest of the file.
What separates a strong certification from a weak one is detail about effects, not about the diagnosis. The practitioner is describing how long a task takes, how often help is needed, and what the person cannot do on their own even with therapy, medication and devices. A form that names a condition and stops there gives the CRA very little to assess, which is how a genuine case ends up refused.
What does DTC approval unlock beyond the tax credit?
Approval does more than lower a tax bill. It is the gate to a Registered Disability Savings Plan, it is required for the child disability benefit alongside the Canada child benefit, and it opens the disability supplement of the Canada workers benefit. That is why people apply even when they owe no tax.
| What approval unlocks | What it is | Key condition or amount |
|---|---|---|
| RDSP | A registered savings plan for long-term security | DTC approval is required to open and to maintain the plan |
| Child disability benefit | A monthly amount paid alongside the Canada child benefit | Up to $3,480 per year, or $290.00 per month, per eligible child, July 2026 to June 2027 |
| Canada workers benefit disability supplement | An extra amount for workers with lower income | Up to $843 for the 2025 tax year |
| Past year adjustments | Reassessment of returns already filed | Up to 10 years of earlier claims |
The child disability benefit requires eligibility for both the Canada child benefit and the DTC. It starts to be reduced once adjusted family net income passes $82,847, at 3.2 percent of the excess for one eligible child and 5.7 percent for two or more. The CRA child disability benefit page sets out the calculation.
Do not confuse that with the Canada Disability Benefit, a separate and newer federal program. Its maximum is $204.20 per month for July 2026 to June 2027, based on the 2025 return, after $200 per month for the previous period based on the 2024 return. A fixed $150 supplemental payment starts in Fall 2026 to help offset the cost of obtaining the DTC, with no application needed.
The RDSP link is the one most families underestimate. Approval is what makes the plan possible at all, and once it is in place the account can receive federal grants and bonds. If that is your goal, our RDSP opening service picks up where the DTC decision leaves off.
Can unused amounts be transferred to a family member?
If the approved person does not need the full amount to reduce their own tax to zero, the unused part can be transferred to a spouse, common-law partner or supporting family member. That transfer is what makes the credit useful for households where the person with the impairment has little or no taxable income.
| Line number | Purpose | Who normally uses it |
|---|---|---|
| 31600 | Disability amount for self | The approved person |
| 31800 | Disability amount transferred from a dependant | A parent or other supporting family member |
| 32600 | Amounts transferred from a spouse or common-law partner | The partner claiming the unused amount |
| 21400 | Child care expenses | A parent, and it can reduce the under 18 supplement |
| 21500 | Disability supports deduction | The person paying for supports needed to work or study |
| 33099 or 33199 | Medical expenses, including the practitioner fee for completing the form | Whoever claims the household medical expenses |
Decide who claims before filing, not after. Once returns are filed, moving an amount between two people means adjusting both, which is slower than getting it right the first time. If several years are approved at once, the same decision has to be made for each year, since incomes change.
Where should you start?
Start by confirming that the impairment is severe and prolonged, then book time with the practitioner who knows the file best, since Part B carries the application. Use the latest Form T2201, keep a copy, and plan the claim years before filing. Our team can walk through the steps with you.
No one can promise an approval, and anyone who does is selling something. What you can control is the quality of the certification, the version of the form, and whether the claim actually reaches the return once a decision arrives. Those three things decide most outcomes.