Claim the Disability Tax Credit up to 10 years back
Can I claim the Disability Tax Credit for past years?
DTC retroactive claim guide: compare 10 years of amounts, learn how CRA reassessments work, and see why past eligibility matters for an RDSP.


Yes. If the Canada Revenue Agency approves your Disability Tax Credit eligibility for earlier tax years, you can ask it to reassess filed returns for up to 10 years. The result depends on tax owed in each year, available transfers, and whether the under-18 supplement applied. Approval never guarantees a specific refund.
The stakes are easiest to see year by year. For 2025, the federal disability amount is $10,138 for someone 18 or older. At the federal non-refundable rate of about 15%, that amount reduces federal tax by roughly $1,500 when enough tax is otherwise payable. Earlier approved years can be reassessed separately.
| What you need to know | Verified answer |
|---|---|
| Retroactive window | Up to 10 years |
| 2025 disability amount, 18 and older | $10,138 |
| 2025 supplement for a child under 18 | $5,914 |
| 2025 combined amount for a child under 18 | $16,052 |
| Type of credit | Federal non-refundable tax credit |
Use the table as a map, not as a refund quote. The amount entered on a return is not the same as cash paid. Tax owing, transfers to a supporting family member, and the child supplement reduction rule can change the result. The REEI.ca calculator can help you organize an estimate before a formal reassessment.
Can I claim the Disability Tax Credit for past years?
Yes, after the CRA approves DTC eligibility for those earlier years. You then claim the disability amount on each applicable filed return or transfer an unused amount to an eligible supporting family member. The CRA reassesses the returns separately, so one approved period can produce different results from year to year.
DTC approval and the tax claim are separate. A medical practitioner certifies the effects of the impairment during the application stage. The CRA decides which years meet the eligibility rules. Once approved, the disability amount is claimed on the return for each recognized year. Do not assume that the approval notice itself confirms a refund.
Start by reading the years listed in the CRA decision. Match those years to returns already filed. Check whether the disability amount was claimed by the person with the disability, transferred from a dependant, or transferred from a spouse or common-law partner. The claimant can differ across years when family circumstances or tax payable changed.
The federal DTC is non-refundable. It reduces federal tax that would otherwise be owed. If the full amount cannot be used by the person with the disability, an eligible supporting family member may be able to use an unused portion. Excess credit is not paid simply because the CRA approved eligibility.
How far back can a DTC claim go?
A retroactive DTC claim can reach back up to 10 years, but only for tax years the CRA approves. The window does not make every past year eligible automatically. The medical information must support the effects of the impairment during each year, and a reassessment can only change a return that was filed.
The practical starting point is the CRA decision, not the date you first heard about the DTC. If the decision recognizes earlier years, review the corresponding notices of assessment and returns. If it recognizes fewer years, do not request amounts for periods outside the approved eligibility dates.
That distinction matters for families who have managed an impairment for a long time but applied recently. A current approval may include a past period, yet the approved start year still controls the claim. The CRA guide to claiming the DTC is the official reference for the retroactive window and claim process.
Keep a year-by-year worksheet. Record the approved year, who paid federal tax, whether the disability amount already appeared on the return, and whether a supporting person may use an unused amount. This prevents one family member from assuming that the same claim route applies throughout the approved period.
How much is the DTC for each past year?
The disability amount changes by tax year. For an adult claim, use the disability amount listed for that year. For a child under 18, the supplement may apply in addition to the disability amount, subject to its reduction rule. These figures are claim amounts, not promised refund amounts or approval estimates.
| Tax year | Disability amount | Supplement for a child under 18 |
|---|---|---|
| 2025 | $10,138 | $5,914 |
| 2024 | $9,872 | $5,758 |
| 2023 | $9,428 | $5,500 |
| 2022 | $8,870 | $5,174 |
| 2021 | $8,662 | $5,053 |
| 2020 | $8,576 | $5,003 |
| 2019 | $8,416 | $4,909 |
| 2018 | $8,235 | $4,804 |
| 2017 | $8,113 | $4,733 |
| 2016 | $8,001 | $4,667 |
The table shows why a single headline amount cannot describe a retroactive claim. The base amount rose from $8,001 in 2016 to $10,138 in 2025. The child supplement rose from $4,667 to $5,914 over the same listed years. Each return must use its own year's amount.
For 2025, the combined amount for a child under 18 is $16,052 before any applicable supplement reduction. The supplement is reduced if someone claimed child care expenses on line 21400 or attendant care expenses on line 33099 or 33199 for the child, or if the child claimed attendant care expenses on line 21500 or 33099.
| Claimant situation | Amount to review | Key limit |
|---|---|---|
| Person 18 or older | Disability amount for the applicable year | Non-refundable and limited by tax otherwise owed |
| Child under 18 | Disability amount plus the applicable supplement | Supplement may be reduced by listed child care or attendant care claims |
| Supporting family member | Unused disability amount that can be transferred | Transfer depends on eligibility and the tax situation for that year |
Do not add the table rows and treat the result as a refund. The federal tax reduction is based on the non-refundable rate and tax payable in each year. A person who paid little federal tax may use less of the amount, while a valid transfer may let a supporting family member claim an unused portion.
How do I request a reassessment for past tax returns?
First obtain DTC approval for the earlier years. Then compare the approved period with returns already filed and request a change for each applicable year. Identify the correct disability amount line and claimant. The CRA reassesses each return, applies the non-refundable credit against tax otherwise owed, and issues the resulting notice.
| Adjustment route | When it fits | What to identify |
|---|---|---|
| Request through a CRA account | You can access the filed return and request changes online | Approved tax year, claimant, and applicable disability amount line |
| ReFILE through supported tax software | Your software supports changes to an already filed return | The return being changed and the corrected claim |
| Paper adjustment request | You cannot or prefer not to use an online adjustment route | Tax year, requested change, and supporting details |
| CRA adjustment connected to the DTC application | The current application route offers a request to adjust applicable past returns after approval | Consent, approved period, and any transfer information the CRA needs |
Whichever route you use, the tax return must already exist. Ask for a reassessment, not a second original return. Use line 31600 for the disability amount for self, line 31800 for an amount transferred from a dependant, or line 32600 for amounts transferred from a spouse or common-law partner.
Do not request the same amount through several routes. Keep copies of the request and the revised notices of assessment. Compare the CRA result with the year, claimant, and line you submitted. If a transfer was intended, confirm that the CRA applied it to the supporting person's return rather than only noting the DTC holder's eligibility.
The CRA may need enough information to connect the DTC approval with the filed return. A clear request names the tax year, the correct line, and the person making the claim. REEI.ca's English application page can help you start the DTC process before any past-return adjustment.
What should I gather before requesting DTC adjustments?
Gather the CRA DTC decision, the filed returns and notices of assessment for every approved year, and records showing who could claim or receive a transfer. For a child claim, also review child care and attendant care expenses. Organizing these records by year makes the reassessment request easier to check.
| Record | Why it matters | What to check |
|---|---|---|
| CRA DTC decision | Defines the years the CRA approved | Approved start and end years |
| Filed tax return | Shows whether the disability amount was already claimed | Lines 31600, 31800, and 32600 |
| Notice of assessment | Provides the CRA's existing assessment for the year | Tax payable and any prior adjustment |
| Supporting family member's return | Helps assess whether an unused amount can be transferred | Relationship, support, and tax otherwise owed |
| Child care and attendant care records | May affect the under-18 supplement | Lines 21400, 21500, 33099, and 33199 |
| Medical practitioner fee receipt | The practitioner fee for completing the form may be a medical expense | Whether it belongs on line 33099 or 33199 |
A clean worksheet should show one row per approved year. Keep the adult or child status for that year, the amount from the official table, the original claimant, the proposed claimant, and the adjustment route used. This is more reliable than treating the retroactive period as one large claim.
If the person moved between provinces, provincial or territorial disability amounts may differ. Do not copy a federal figure into the provincial section. Provincial amounts and rates vary, so check the return and official guidance for the province that applied in each tax year.
How can retroactive DTC amounts stack across years?
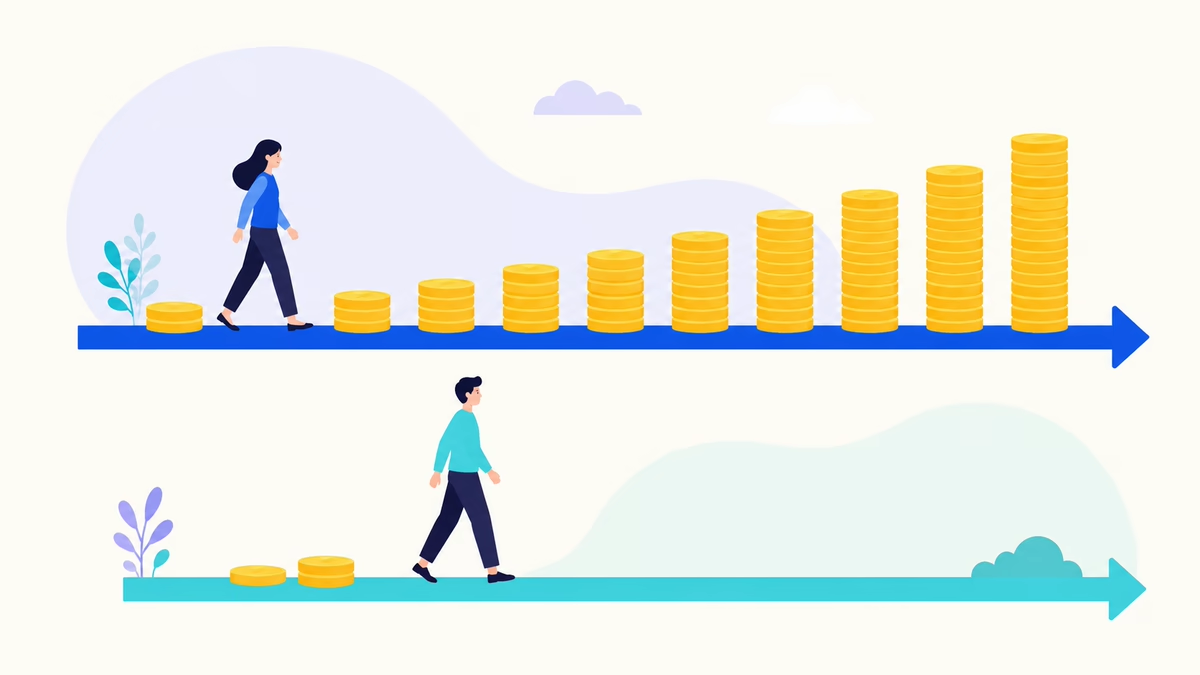
They stack through separate reassessments, not as one flat payment. Each approved year has its own disability amount, tax payable, claimant, and possible transfer. A child supplement may also apply for years the person was under 18. The CRA's result is the combined effect of those year-specific changes.
Consider the listed period from 2016 through 2025. The adult disability amount is different in every row, and the applicable child supplement is also different. The CRA uses each year's tax rules and return. That is why a person approved across the period should expect several adjusted calculations, not one percentage applied to one total.
The 2025 adult amount illustrates the mechanics. The disability amount is $10,138. At the federal non-refundable rate of about 15%, it reduces federal tax by roughly $1,500 when enough federal tax is otherwise owed. If less tax was owed, the usable value may be lower unless an eligible supporting family member can claim an unused portion.
For a child under 18 in 2025, the combined amount is $16,052 before any required supplement reduction. The base and supplement still do not equal a cash refund. The reassessment applies the eligible non-refundable amount against tax otherwise payable by the claimant or an eligible supporting family member.
A careful estimate therefore uses the annual amounts, the tax paid in each year, and the transfer rules. It also flags child care or attendant care claims that may reduce the supplement. This produces a range of plausible tax effects without promising a refund the CRA has not calculated.
Which tax return lines matter for a retroactive DTC claim?
The main line depends on who uses the disability amount. Use line 31600 for the person with the disability, line 31800 for an amount transferred from a dependant, and line 32600 for amounts transferred from a spouse or common-law partner. Other listed lines can affect a child's supplement or related deductions.
| Tax return line | Purpose | Why to review it |
|---|---|---|
| 31600 | Disability amount for self | Confirms whether the approved person claimed the amount |
| 31800 | Disability amount transferred from a dependant | Shows a supporting person's claim for an unused amount |
| 32600 | Amounts transferred from a spouse or common-law partner | Shows a spousal transfer |
| 21400 | Child care expenses | May reduce the supplement for a child under 18 |
| 21500 | Disability supports deduction | Can be relevant when the child claimed attendant care expenses |
| 33099 and 33199 | Medical expenses, including a practitioner's fee for completing the form | Attendant care claims may affect the child supplement |
Review these lines for every approved year rather than copying the newest return. A transfer may be useful in one year and unnecessary in another because tax payable changed. The family relationship and support conditions must also fit the year being adjusted.
How does retroactive DTC approval affect an RDSP?
DTC approval is required to open and maintain a Registered Disability Savings Plan. Earlier approved DTC years can also matter when reviewing RDSP grant and bond entitlement carry-forward. The tax reassessment and the RDSP review are separate, so completing one does not automatically confirm what the other will produce.
After approval, confirm the DTC eligibility period before opening the plan. A longer approved period may change which prior grant and bond entitlements can be considered under RDSP carry-forward rules. Do not assume the tax refund and RDSP value are the same, or that a retroactive tax adjustment deposits money into the RDSP.
An RDSP is a long-term savings plan. The disability amount is a tax credit. Grants and bonds follow their own eligibility rules. Keep the CRA DTC decision because it anchors both the tax-year review and the RDSP discussion. REEI.ca can help with opening an RDSP after DTC approval.
What changed for Form T2201 in 2026?
Since July 14, 2026, the general submit-documents section of a CRA account can no longer be used for DTC applications unless the CRA asked for more information. As of September 8, 2026, the CRA will no longer accept pre-2023 versions of Form T2201. Use the current online or paper route.
The online DTC application in a CRA account is processed faster than paper. A paper applicant must download the latest 2023 or later T2201 and mail it to the correct tax centre. The CRA's 2026 application update explains the change, and the official T2201 page provides the current form.
The September 8, 2026 cutoff matters before the reassessment stage. An outdated T2201 can block the application that must come first. If you already have DTC approval for the past years, focus on the tax adjustment route instead of sending another application through the discontinued document-upload path.
What should Quebec applicants check?
Quebec residents follow the federal CRA process for the DTC and federal return adjustments. Provincial disability amounts and rates can differ, so review the Quebec return separately and do not assume the federal amounts apply. For every approved year, keep the federal reassessment and provincial review as distinct tasks.
The ten-year table in this guide contains verified federal amounts only. It does not quote a Quebec disability credit amount. If a federal DTC reassessment changes income-tax information that also belongs on a Quebec return, check the applicable provincial process for that year using official Quebec guidance.
What should I do after the CRA approves the DTC?
Read the approved eligibility years, compare them with filed returns, and choose the correct claimant for each year. Request the tax adjustments, verify every revised notice, and then review RDSP opening and carry-forward questions separately. Keep the CRA decision, returns, and adjustment records together for future renewals or corrections.
Do not treat approval as the finish line. The practical value comes from accurate year-by-year claims, valid transfers, and a separate RDSP review. If a revised assessment does not match the requested year or line, compare it with your saved request before taking the next step.