Tax implications of RDSP withdrawals
Which parts of an RDSP withdrawal are taxable?
Which parts of an RDSP withdrawal are taxable, how the T4A and line 12500 work, and when the three-to-one grant repayment rule applies.

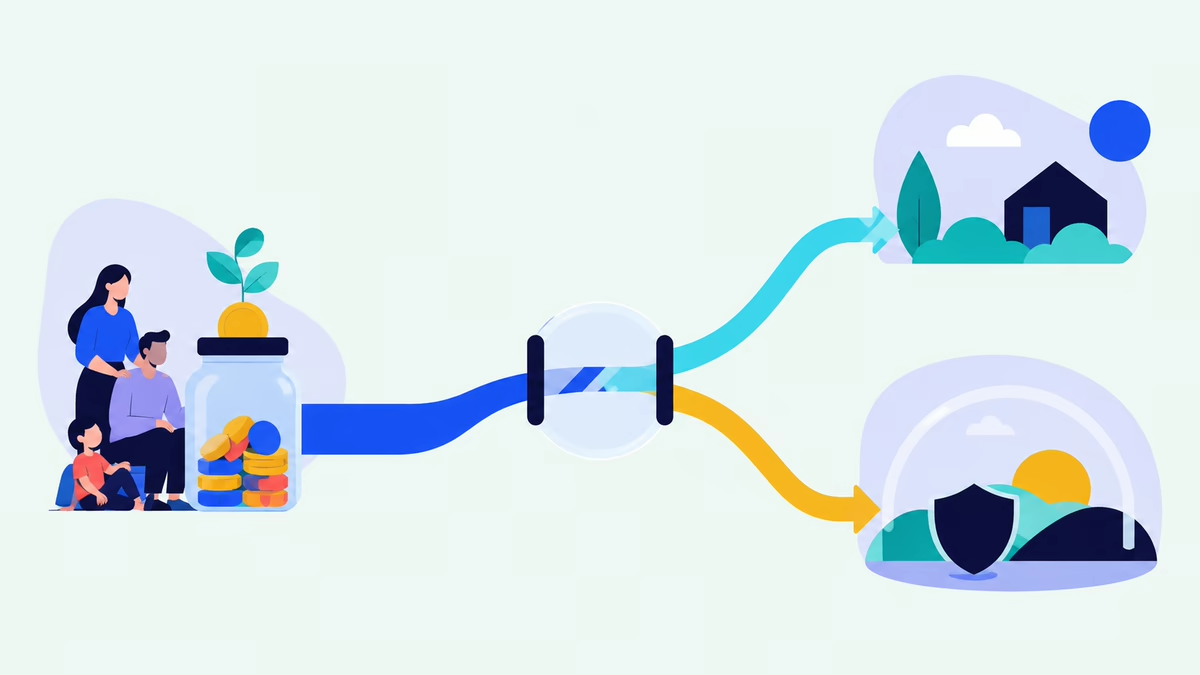
An RDSP withdrawal is not one thing. Every payment out of the plan carries a proportional slice of what is inside it, and the Canada Revenue Agency taxes most of that. Private contributions come out untaxed because they were never deducted going in. Government assistance, meaning grant and bond, plus investment income and any rollover proceeds, is taxable to the beneficiary in the year the money is received.
The tax bill is usually the smaller problem. The bigger one is repayment. Take money out too early and the government claws back $3 of grant and bond for every $1 withdrawn, which can dwarf whatever tax is owed. Understanding both at once is the only way to time a withdrawal sensibly.
What follows is the treatment set out by the Canada Revenue Agency and Employment and Social Development Canada. It applies to the beneficiary, not to the plan holder, and it is deliberately built to make long holding periods more attractive than short ones. Our overview of the Registered Disability Savings Plan covers how the plan works before withdrawals begin.
Which parts of an RDSP withdrawal are taxable?
Private contributions are never taxed on the way out, because they were made with after-tax dollars and were never deductible. The Canada Disability Savings Grant, the Canada Disability Savings Bond, investment income earned inside the plan, and proceeds from rollovers are all included in the beneficiary's income when they are paid out.
| Component of the plan | Taxable when withdrawn | Why |
|---|---|---|
| Private contributions | No | They were not deductible when made, so they are returned untaxed. |
| Canada Disability Savings Grant | Yes | Government money that has never been taxed in the beneficiary's hands. |
| Canada Disability Savings Bond | Yes | Same treatment as the grant. |
| Investment income earned in the plan | Yes | Growth was sheltered while inside the plan, not exempted. |
| Proceeds from a rollover | Yes | The transferred amount came from a plan where tax had been deferred. |
You cannot choose which component comes out. Every payment carries a proportional slice of each amount available, so a plan that is mostly grant and bond produces a mostly taxable withdrawal. A plan built largely on private contributions produces a much smaller taxable share. Where your money came from is covered on our page about accessing government grants and bonds.
The split matters for a practical reason. A plan built mostly on bond and grant, which is the normal shape for a low income beneficiary, produces a payment that is almost entirely taxable. A plan built on private contributions and a large rollover produces one that is mostly not. Two beneficiaries can withdraw the same dollar amount in the same year and report very different income.
One detail matters for anyone who has already repaid grant or bond. Amounts that were previously included in income and then repaid to the government are deductible, and the Canada Revenue Agency directs those to line 23200 of the return. That deduction is easy to miss and worth raising with whoever prepares the return.
How is the taxable portion calculated and reported?
The issuer works out the non-taxable share using a formula in the Income Tax Act that compares contributions still in the plan against the plan's value above the assistance holdback amount. Everything else in the payment is taxable. The issuer reports that taxable amount in box 131 of a T4A slip.
| Stage | Who is responsible | What appears |
|---|---|---|
| Payment is calculated | The RDSP issuer. | A proportional mix of contributions, grant, bond and investment income. |
| Non-taxable share determined | The RDSP issuer. | The lesser of the payment itself and the amount produced by the statutory formula. |
| Slip issued | The RDSP issuer. | T4A slip, taxable amount in box 131 of the Other information area. |
| Income reported | The beneficiary. | Line 12500 of the income tax and benefit return. |
| Repaid amounts deducted | The beneficiary. | Line 23200, for amounts previously included in income. |
The slip arrives in the beneficiary's name even when a parent or a legal representative manages the plan, and the amount belongs on the beneficiary's return rather than the holder's. Two copies of the T4A go to the beneficiary or their legal representative. The income belongs to the beneficiary, not the holder, which is the point of the whole structure. A beneficiary with little other income often pays little or no tax on the taxable portion, because it lands on a low marginal rate and is reduced by personal credits.
Employment and Social Development Canada notes that opening and contributing to a plan does not affect other federal or provincial benefits anywhere in Canada. Withdrawals are a separate question. In Quebec, New Brunswick and Prince Edward Island, withdrawals may affect provincial benefit amounts, so check with the provincial program before taking a payment.
What is the assistance holdback amount and the three-to-one rule?
The assistance holdback amount is the total grant and bond paid into the plan in the previous ten years, less anything already repaid. Issuers must hold it in reserve. Since 2014, withdrawing money triggers a proportional repayment of $3 for every $1 taken out, capped at that holdback amount.
| Event | Rule applied | Amount repaid |
|---|---|---|
| A withdrawal is made | Proportional repayment rule. | $3 for every $1 withdrawn, up to the assistance holdback amount. |
| The plan is closed voluntarily | Ten-year repayment rule. | The full assistance holdback amount. |
| The plan ceases to be registered | Ten-year repayment rule. | The full assistance holdback amount. |
| The beneficiary dies | Ten-year repayment rule. | The full holdback amount, with the remainder going to the estate. |
| Disability Tax Credit approval is lost before 60 and money is withdrawn | Proportional repayment rule. | $3 for every $1 withdrawn, capped by the grant and bond inside the applicable age and loss window. |
The Canada Revenue Agency publishes a worked example that makes the difference concrete. A beneficiary who opens a plan in 2020 and contributes $1,500 every year, collecting the maximum $3,500 of grant each time, has an assistance holdback amount of $21,000 by 2025. Withdrawing $600 that year repays $1,800, roughly nine percent of what closing the plan outright would have cost.
Repayments are attributed to the grants and bonds in the order they were paid into the plan, oldest first. That ordering quietly works in the beneficiary's favour, because the oldest amounts are the ones closest to aging out of the ten-year window anyway. Our page on the 10-year rule for RDSP withdrawals goes through the timing in detail.
There is also a hard floor on any payment. A disability assistance payment cannot be made if, afterward, the fair market value of the plan would fall below the assistance holdback amount. A plan heavy in recent grant can therefore be effectively locked, not by a rule about withdrawals, but by simple arithmetic.
What are LDAPs and DAPs, and when must payments start?
A disability assistance payment is any payment from the plan to the beneficiary or their estate. A lifetime disability assistance payment is the recurring version. Once started it must be paid at least annually, and it must begin by the end of the year the beneficiary turns 60 unless the plan is a specified disability savings plan.
| Feature | Lump sum disability assistance payment | Lifetime disability assistance payment |
|---|---|---|
| Frequency | One-off, requested each time. | Recurring, at least once a year. |
| Must it be offered | No. Issuers set their own rules on lump sums. | Yes. Every plan must support them. |
| Deadline to begin | None. | The end of the calendar year the beneficiary turns 60, unless the plan is a specified disability savings plan. |
| Annual ceiling | Limited by the holdback floor and, in some years, the plan's status. | Capped by a statutory formula based on plan value and the beneficiary's age. |
| When it ends | When the plan runs out of eligible funds. | When the beneficiary dies or the money is gone, at which point the plan closes. |
The lifetime payment ceiling is set by a formula that divides the plan's fair market value at the start of the year by the greater of 80 and the beneficiary's age, plus three, minus their actual age. The practical effect is that the annual maximum rises as the beneficiary gets older, spreading the plan across a normal lifespan rather than a few large payments.
Between the ages of 27 and 58 at the start of the year, the beneficiary has the right to direct that payments be made to them, provided the plan value stays above the holdback amount afterward. That right sits with the beneficiary, not the holder, which matters in plans where those are different people.
What changes if the plan is primarily government assisted?
A plan is primarily government assisted for a year when the grant and bond paid into it and into any prior RDSP of the beneficiary before that year exceed the contributions made before that year. In such a year, payments are capped at the greater of the lifetime formula and 10 percent of plan value.
| Situation | Effect on withdrawals |
|---|---|
| Primarily government assisted plan | Payments capped at the greater of the statutory formula and 10 percent of plan value. |
| Specified year, life expectancy of five years or less | No formula ceiling, and up to $10,000 a year in taxable savings without triggering repayment. |
| Beneficiary over 59 | Lifetime payments are limited to the statutory formula. |
| Disability Tax Credit lost and the holder terminates the plan | No limit on the amount withdrawn, but the full amount inside the applicable window is repaid. |
The test runs each year and it looks past the current plan. Grant and bond paid into an earlier RDSP for the same beneficiary count on the government side, and contributions made to that earlier plan count on the private side, which is why moving an account between issuers does not reset the calculation.
The specified year rule is the one exception with real flexibility. When a doctor or nurse practitioner certifies in writing that the beneficiary is not expected to live longer than five years, and the certificate reaches the issuer, that year and the five following years allow withdrawals of up to $10,000 a year in taxable plan savings plus a pro-rated share of contributions, free of the repayment obligation. The certificate must be filed in or before the year it is meant to apply to. File it late and the earlier years are simply lost.
When can you withdraw without repaying grant or bond?
Three situations avoid repayment. Grant and bond that entered the plan more than ten years ago are no longer subject to clawback. By December 31 of the year the beneficiary turns 60, withdrawals must begin, outside a specified disability savings plan, and none of the grant and bond is subject to repayment. The specified year election is the third.
That third case exists because the ordinary schedule assumes a long retirement. When a practitioner has certified a life expectancy of five years or less, holding the plan to that schedule would strand money the beneficiary will not live to receive. The election lifts the age 60 starting requirement and the repayment obligation together, inside the annual limit.
That first case is why patience pays so well here. A grant received in 2016 stops being clawback-eligible after 2026, and the assistance holdback amount shrinks accordingly. A plan that has been quiet for a decade can often be drawn on with no repayment at all, which is worth confirming with the issuer before assuming otherwise.
Loss of Disability Tax Credit approval before age 60 is the situation that catches people off guard, because the repayment window is measured from the year approval lapsed rather than the year of the withdrawal. Keeping the certificate current is a financial decision as much as a medical one. Our page on eligibility requirements explains what the approval requires, and our page on contribution limits covers how contributions affect the taxable share of a future payment.
To see what a withdrawal would produce in a specific plan, including the repayment it would trigger, the calculator at reei.ca models the figures against your own numbers. It is a planning tool. The amounts that actually apply are the ones the issuer and Employment and Social Development Canada calculate at the time of payment.
Sources consulted
- Canada Revenue Agency, Registered disability savings plan rules, for which components are included in the beneficiary's income and the non-deductibility of contributions.
- Canada Revenue Agency, What types of payments are made from an RDSP, for the definitions of disability assistance payments, the lifetime payment formula, the non-taxable portion formula and specified years.
- Canada Revenue Agency, How payments from an RDSP are reported, for T4A box 131 and line 12500.
- Canada Revenue Agency, Canada disability savings grant and Canada disability savings bond, for the assistance holdback amount, the proportional repayment rule, the worked repayment example and the line 23200 deduction.
- Canada Revenue Agency, Additional rules if the RDSP is a primarily government-assisted plan, for the 10 percent ceiling and the rights of beneficiaries aged 27 to 58.
- Employment and Social Development Canada, Withdraw money from your plan, for the age 60 start date, the ten-year exemption and the provincial benefit interactions.
Discover our latest articles about RDSP: